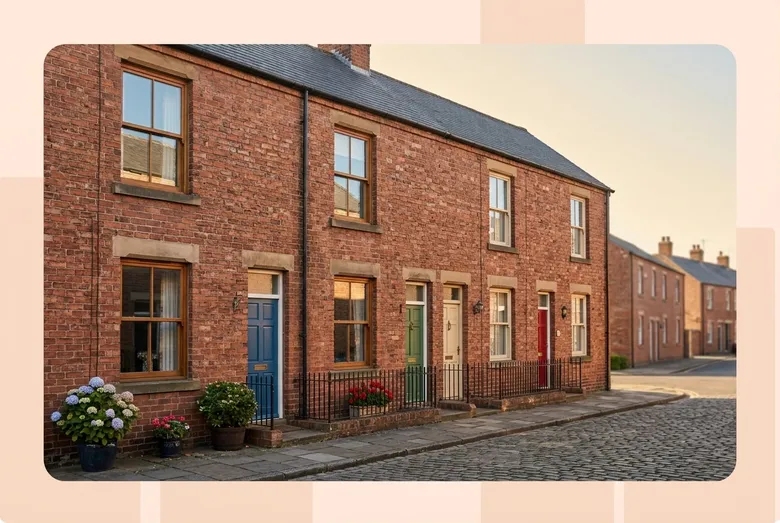
The problem: minimum property values
Most buy-to-let lenders set a minimum value for the property they lend on. Below it, they will not lend at all, however good the rent is. Across the market, minimums commonly sit somewhere between £50,000 and £75,000, and a few are higher.
Plenty of North East terraces sell for £40,000 to £70,000. So a deal that looks brilliant on yield can have only a handful of lenders willing to look at it.
Why lenders avoid low-value homes
- The loan is small, so the fees and admin cost the lender the same as a bigger loan for less return.
- Prices in some low-value streets have been slow to rise, so lenders see more risk if they have to repossess.
- Valuers can be cautious, and down-valuations are more common.
What landlords do about it
- Check the minimum before you offer. Do not assume a mortgage will be available.
- Use specialist lenders, who are more likely to lend on lower values, sometimes at a slightly higher rate.
- Buy in cash or with a bridge, then refinance once there are more lenders, or when you have a portfolio.
- Watch the 5% stamp duty surcharge. It does not apply to properties under £40,000.
Updated November 2026. Lender minimums change. This page gives typical ranges, not a list of named lenders. Use the deal analyser: it flags any property under £75,000.
What is the minimum property value for a buy-to-let mortgage?
It depends on the lender. Many sit between £50,000 and £75,000. A smaller number of specialist lenders go lower.
Can I get a mortgage on a £45,000 house?
It is possible but hard. Only a few lenders will look at it, so many investors buy in cash and refinance later.