The short answer
Development finance is a short-term loan, usually 12 to 24 months, that pays for the land and the build costs in stages. You repay it by selling the finished units or refinancing onto buy-to-let or commercial mortgages.
How lenders size the loan
- Loan to cost (LTC). The share of the total cost (land plus build) the lender will fund, often up to 70% to 90% of build costs and 50% to 70% of the land.
- Loan to gross development value (LTGDV). The total loan compared with what the finished scheme will be worth, often capped at 60% to 70%.
- The lower of the two limits wins. The rest is your equity.
A worked example
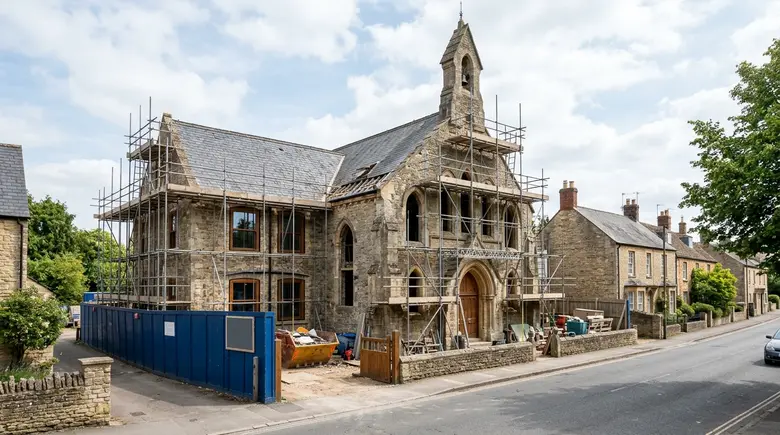
You buy a former chapel for £150,000 and plan four flats costing £320,000 to build. The finished flats are valued at £680,000 in total. Total cost is £470,000. At 65% LTGDV the lender can lend up to £442,000, including interest and fees. You would need to fund the rest, about £28,000 plus interest and fees, from your own money.
How the money is paid
The land part is usually paid on day one. Build money is released in stages (drawdowns) after a monitoring surveyor visits and confirms the work is done. Interest is usually charged only on what you have drawn and is often rolled up into the loan.
What lenders want to see
- Full planning permission and building regulations approval, or a clear route to them.
- A detailed cost schedule and a fixed-price or well-priced build contract.
- Your experience, or a professional team (architect, contractor, project manager) that has done it before.
- Evidence of sale values or rents from a local agent.
- A contingency, often 5% to 10% of build costs.
- A clear exit: sales, or a refinance once the units are let.
Light refurbishment or full development?
If you are not changing the structure or needing planning, a refurbishment bridging loan is often simpler and cheaper. Conversions, extensions that need planning and new builds usually need development finance.
Is it regulated?
Development finance for properties you will sell or let is not regulated by the FCA. If you or a family member will live in one of the units, part of the lending may be regulated.
Common questions
Can I get development finance with no experience?
Some lenders will fund a first small scheme if your professional team is experienced and the numbers leave a good margin. Expect a lower loan and closer monitoring.
What profit margin do lenders want?
Many want to see a profit on cost of at least 15% to 20%, so the scheme can absorb overruns and still repay the loan.
How long does development finance take to arrange?
Often four to eight weeks, longer for bigger schemes, because the lender reviews costs, planning and your team in detail.