When landlords use a bridge
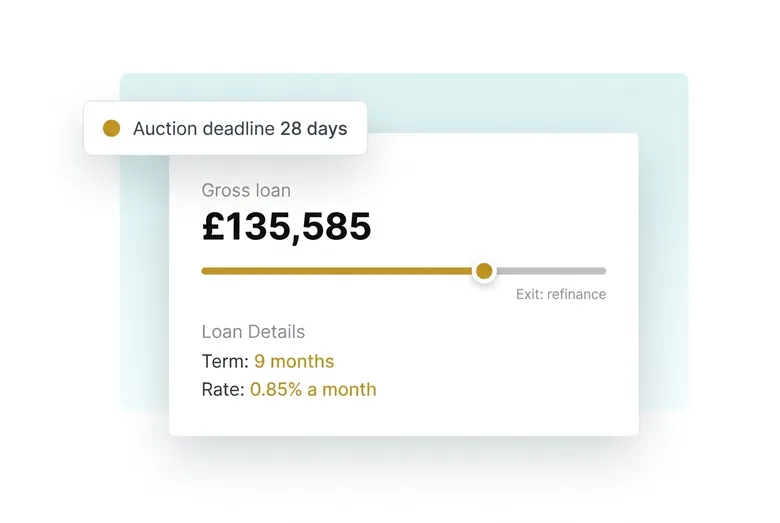
- Auctions. You usually have 28 days to complete. Most buy-to-let lenders cannot move that fast.
- Unmortgageable property. No kitchen, no bathroom, or major works. A bridge funds the purchase and the works, then you refinance onto a buy-to-let.
- Buy, refurbish, refinance. Add value, get it revalued, and pull money back out.
- Chain breaks on investment property.
How the cost works
Bridging interest is quoted monthly, often between 0.6% and 1.2% a month. Most bridges retain the interest: the lender adds the whole term's interest to the loan on day one, so you pay nothing monthly but borrow more.
On top of interest there is usually an arrangement fee of around 2%, legal and valuation costs, and sometimes an exit fee.
A worked example
You need £120,000 for 9 months at 0.85% a month, with a 2% arrangement fee and £2,500 of legal and valuation costs, interest retained.
Gross loan = (£120,000 + £2,500) ÷ (1 − 0.02 − 0.0085 × 9) = £135,585. Total interest is about £10,372 and the arrangement fee about £2,712.
The exit plan matters most
Lenders care more about how you will repay than almost anything else. Usually that is a sale or a buy-to-let mortgage once the works are done. Have the refinance numbers ready: run them through the deal analyser.
How fast can a bridging loan complete?
Often two to four weeks, sometimes faster if the valuation and legal work move quickly. Auction deadlines are usually 28 days.
How much can I borrow on a bridging loan?
Most lenders go up to 70% to 75% of the property's value, including the retained interest and fees. Some will lend more with extra security.